
16 Feb How to File Car Accident Claim
If you are currently navigating the bureaucratic aftermath of a collision, understanding how to file car accident claim in Florida requires more than just filling out forms; it demands a strategic alignment with state-specific mandates. The procedural window is unforgiving: you must report the incident to the authorities, secure clinical diagnostic imaging within a strict 14-day interval, and provide formal notification to your carrier. Florida’s no-fault statutes are designed to streamline recovery, yet they often function as a labyrinth of red tape that can jeopardize your financial solvency if a single step is mismanaged.
The immediate aftermath of a high-velocity impact is a period of high adrenaline and low clarity. While Florida’s no-fault framework was theoretically established to mitigate the burden on the court system, it has simultaneously created a rigid set of hurdles for the uninitiated. Precision in the early stages is paramount. Mastering the technical nuances of how to file car accident claim properly is often the only barrier between a fully funded recovery and a permanent financial loss.
Get a Free Consultation
Call us at (813) 598-4868
Table of Contents
ToggleKey Takeaways
- Initiate a formal police report immediately at the scene to ensure a neutral, third-party record of the environmental conditions and vehicle positioning.
- Validate your clinical status within the 336-hour statutory window, as the Florida PIP system will summarily reject any claim for benefits if the initial medical touchpoint occurs on day 15.
- Strictly observe the two-year litigation deadline codified in recent Florida legislative updates, ensuring your right to sue remains active under the statute of limitations.
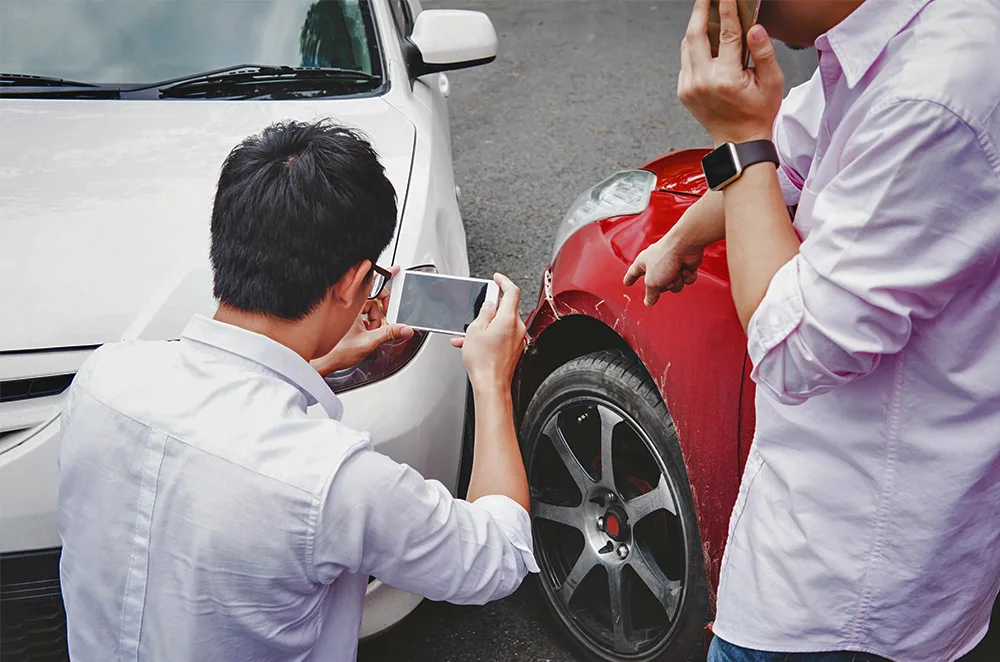
- Curate a comprehensive evidentiary dossier that includes high-fidelity site photography, repair estimates from a certified technician, and a chronological log of lost professional hours.
- Engage high-level legal counsel to serve as the primary conduit for all insurance communications, preventing the accidental disclosure of statements that could be weaponized to mitigate your payout.
The Mechanics of Personal Injury Protection (PIP)
Under the standard Florida PIP policy, the following benefits are accessible:
- 80% reimbursement for medically necessary diagnostic and treatment services.
- 60% indemnification for verifiable loss of income resulting from the trauma.
- Specific, capped death benefits for qualifying survivors in fatal incidents.
Crucially, PIP is silent on the matter of property damage or the intangible toll of pain and suffering. If your clinical diagnosis reveals a permanent loss of bodily function or significant scarring, you may exit the no-fault silo to pursue a broader liability claim. Mastering how to file a car accident claim involves knowing exactly when and how to cross that threshold.
Statutory Deadlines and the Florida Clock
In Florida, time is a commodity that depreciates rapidly after a crash. Missing a single filing window can lead to an immediate dismissal of your rights by a judge.
The Statute of Limitations
Recent changes in Florida law have tightened the window for personal injury suits to two years. This is a critical departure from previous four-year standards and requires a much faster transition from “investigation” to “litigation.”
The 14-Day PIP Trigger
If you do not present yourself to a licensed medical professional within 14 days, your PIP coverage effectively vanishes. This leaves you personally liable for every hospital bill and diagnostic scan. When researching how to file car accident claim, timing should be your highest priority.
Overcoming Procedural Obstacles
Even the most organized claimant can face institutional resistance.
Denied Claims
Insurers frequently deny claims based on “lack of medical necessity” or alleged “gaps in treatment.” We counter these denials with expert medical testimony and forensic data that prove the trauma was a direct result of the collision.
Contested Liability
If the at-fault driver claims you were the primary aggressor, we utilize accident reconstructionists to analyze skid patterns and electronic control module data. In the district, proving the “duty of care” was breached is essential for recovery.
The “Insignificant Injury” Defense
Carriers often argue that low-impact collisions cannot cause spinal damage. We use biomechanical experts to show how the energy transfer in a rear-end hit can cause internal shearing even without significant metal deformation.
Recoverable Damages in the Florida Circuit
A comprehensive claim seek to make the victim whole through both economic and qualitative restitution:
- Full medical overhead, including future surgical projections.
- Documented lost wages and diminished professional longevity.
- Property restoration or total loss valuation.
- General damages for pain, suffering, and loss of life’s enjoyment.
Conclusion
Navigating the intricacies of how to file car accident claim in the state of Florida is a high-stakes endeavor that leaves no room for error. From the 14-day medical trigger to the two-year statutory sunset, every tactical decision influences your final recovery.
Insurance conglomerates move with calculated speed to minimize their exposure; you must respond with equal precision. If you are struggling with the aftermath of a collision, Attorney Kevin Sullivan is prepared to provide the high-authority advocacy required to secure your financial future. Contact our offices at (813) 598-4868 to schedule a confidential case audit.

Frequently Asked Questions
What is the legal deadline for a Florida motor vehicle claim?
For most personal injury matters, the limitation is now two years. However, the PIP medical threshold is a mere 14 days from the date of the incident.
What happens if medical costs surpass $10,000?
Once your PIP is exhausted, you must look to the at-fault driver’s Bodily Injury (BI) coverage. If your injuries are “permanent,” you can pursue a full lawsuit for non-economic damages.
Is an attorney required for every claim?
While simple property damage claims can be handled solo, any case involving bodily injury or disputed fault requires professional legal management to avoid being “low-balled” by the carrier.
Can I recover PIP if I didn’t feel pain until day 10?
Yes, as long as you see a doctor by day 14. Latent symptoms are common in cervical and soft-tissue trauma.
Will my premiums increase after filing?
Florida law prohibits carriers from increasing rates solely for filing a non-at-fault PIP claim, though other variables in your driving history may influence future policy costs.
5720 Gall Boulevard, Ste 4
Zephyrhills, FL 33542
27642 Cashford Cir, Suite #110
Wesley Chapel*, FL 33544
5006 Trouble Creek Rd, Ste 205
Port Richey*, FL 33652
Sorry, the comment form is closed at this time.